When Is the Best Time of Year to Buy a House?
Most advice about timing a home purchase focuses on interest rates, inventory charts, and market data. Those things matter, but they do not tell the whole story.
As a real estate agent with a background in architecture and interior design, I look at timing a little differently. After working with buyers, sellers, and homeowners, I’ve found that the best time of year to buy a house has less to do with the month on the calendar and more to do with your personal situation, your long-term plans, and the property in front of you.
Does the Time of Year Actually Matter?
Clients often ask whether spring or summer is really the best time to buy. My honest answer is that the “spring selling season” is overstated in many markets. There isn’t one best month to buy a house that holds true everywhere, and I’d be careful of anyone who tells you otherwise.
Seasonality can matter in certain places, especially where families are trying to move around school schedules, or in tourist, vacation, and university-driven rental markets. Outside of those situations, however, there is not always a clear season that consistently delivers better prices or better opportunities.
What I notice most is human behavior. People are less eager to tour houses when the weather is unpleasant. Snow, heavy rain, extreme heat, or even a string of gloomy days can keep casual buyers at home. For serious buyers, that can create an opportunity because there may be less competition. For sellers, the same principle works in reverse: if someone makes the effort to see your property during bad weather, they are usually more than a casual browser.
What About Buying a House in Winter?
So if you’re comparing seasons, don’t automatically dismiss the so-called off-season. Deep winter, rainy stretches, or the middle of a heat wave can sometimes be productive times to look precisely because fewer buyers are willing to do the same.
The Real Answer: Buy When You’re Ready to Stop Paying Rent or your life situation dictates it.
The bigger question is not whether it’s March, July, or November. It’s whether you’re ready to stop putting money into someone else’s investment and start building your own future or make a change to it. Put another way: when are you ready to buy a house, and what is actually driving the move?
That applies whether you’re a first-time buyer or someone who’s purchased multiple homes before.
When someone tells me they’re tired of sending rent checks every month with little long-term benefit for themselves, that usually tells me more about their timing than any interest rate forecast.
Of course, there are times when the market becomes unstable or prices appear likely to soften. Those moments do happen, but they’re rarer and much harder to predict than many people believe. If you need a place to live, or a larger or smaller one, and plan to stay there for the long term, I usually think in terms of seven years or more, then the decision becomes less about finding the perfect market moment and more about whether the numbers and the property make sense.
At that point, I focus on questions such as:
• Are there strong loan options available right now?
• Could refinancing be realistic later if rates improve?
• Is the property itself a genuinely good opportunity?
Sometimes getting the right house is the ‘win’. Not every purchase has to perform like a short-term investment.
What If You’re Buying Purely as an Investment?
If you’re looking at a property strictly as a financial transaction rather than a place to live, the conversation changes.
The search criteria become different. Whether it’s your first investment purchase or your fifth, it’s important to understand what’s driving the decision: lifestyle or return on investment. That answer changes how we search, how we evaluate risk, and how much seasonality should matter.
My goal with every client is simple: find the best house for the least amount of money. But what qualifies as “best” depends entirely on what the buyer is trying to accomplish.
Why Waiting for Rates to Drop Can Backfire
One idea I push back on frequently is the belief that buyers should automatically wait for interest rates to fall before making a move.
The problem is that many buyers are waiting for the exact same signal. When rates finally drop, large numbers of buyers often enter the market at once. Increased competition can drive prices higher and reduce much of the savings buyers hoped to gain from a lower interest rate. Freddie Mac publishes the national average rate every week, so you can see for yourself how much it actually moves.
The purchase price is the part you generally cannot renegotiate later. Your interest rate, on the other hand, may be temporary if you’re able to refinance in the future.
Buying well, choosing the right property, and improving its value over time can matter just as much as the rate you start with.
In many situations, I’d rather help a buyer secure the right property and then look for smart, affordable ways to build value than have them sit on the sidelines waiting for the perfect interest rate while opportunities pass by.
The Fixer-Upper Factor: What My Design Background Adds
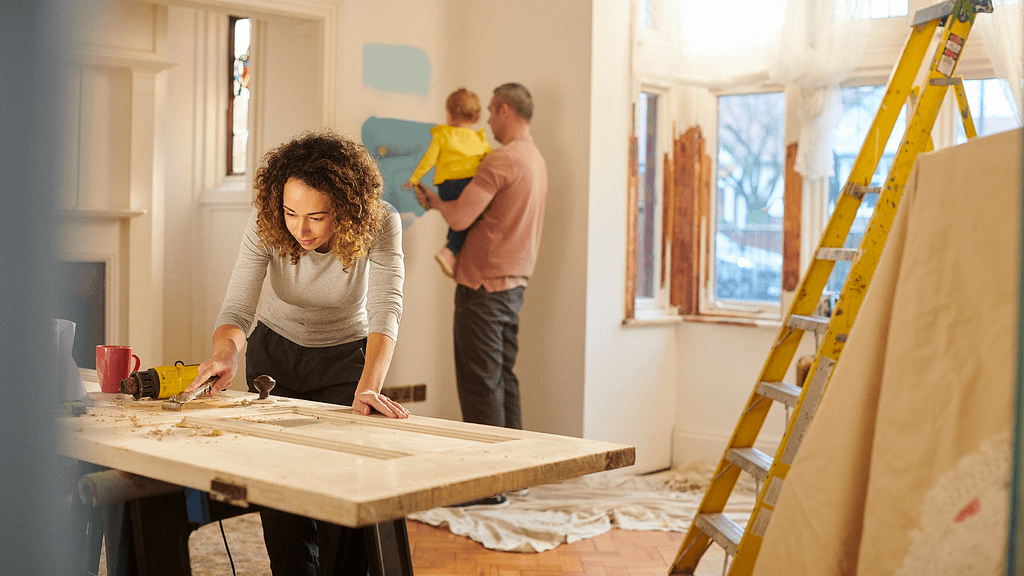
Many buyers are open to the idea of a fixer-upper in theory, especially after years of renovation television and social media content. In practice, though, it’s a different story once budgets, timelines, contractors, and project management become real considerations.
That hesitation is completely understandable. A large renovation estimate for a kitchen, bathroom, or major repair can be enough to scare buyers away from a property that might otherwise be a great fit.
A good agent with renovation experience can help buyers identify which improvements are essential, which can wait, and where money can often be saved by completing work in phases, sourcing materials carefully, or tackling manageable projects themselves.
Many buyers today are stretched thin time-wise or financially. Having a family with children that demand your time and attention, or working long hours or juggling multiple commitments just to afford the mortgage. A renovation can feel overwhelming even when the long-term upside is obvious.
Part of my role as an agent is helping make that potential feel realistic, whether that means breaking projects into smaller stages, connecting clients with the right resources, or exploring financing options that allow improvements to be completed as part of the purchase.
That combination of vision and practicality is one of the biggest advantages of working with an agent who understands renovation and design.
Getting Market Ready Before You Start Looking
When clients ask me about timing, I usually start with their situation rather than the market.
The first step is connecting with a lender and taking an honest look at the full financial picture. Every buyer’s circumstances are different, and there are often ways to strengthen them before making an offer.
Before we seriously begin touring homes, I want clients in the strongest position possible and i want them ready so they dont se the perfect property that they have to pass on because they weren’t. Getting a financial ‘Snapshot’ also prepares you for other costs associated with home ownership so you take those into consideration too when deciding how much you can or should spend.
From there, we start looking strategically. I set clients up on searches and also pay attention to opportunities beyond the standard MLS listings, including:
• Local real estate groups and community networks
• Niche property websites
• Government property listings
• Renovation and rehab-focused sites
• Bank-owned and foreclosure listings
Looking beyond the obvious listings gives buyers a better understanding of what’s truly available, how quickly properties are moving, and where hidden opportunities may exist.
So, When Is the Best Time of Year to Buy a House?
If you’re waiting for the perfect season or the perfect market moment, you may be waiting for something that doesn’t exist. The honest answer is that it’s whenever you’re genuinely ready for it, and that date looks different for everybody.
A better question is:
Am I prepared, and what is really driving this purchase more: the home or the investment?
Get your finances in order first. Be clear about your motivation. Look beyond the obvious listings, and don’t be afraid to search during the “wrong” season if it means less competition.
A fixer-upper, a higher starting interest rate, or imperfect timing should not automatically talk you out of a strong opportunity. Those things can often change over time.
The price you agree to on day one is the one piece of the transaction that tends to stay with you.